2 years ago, HMRC announced changes to the VAT regime within the construction industry. The new reverse charge regime was deferred from 1st October 2019 – 1st October 2020, but due to the Covid pandemic, this deferral was extended until 1st March 2021.
HMRC have not deferred this scheme again, and so the reverse charge VAT will come into effect from 1st March 2021.
So what does this mean for your business?
Who does it apply to?
You must use the reverse charge from 1 March 2021, if you’re VAT registered in the UK, supply building and construction industry services and:
- your customer is registered for VAT in the UK
- payment for the supply is reported within the Construction Industry Scheme (CIS)
- the services you supply are standard or reduced rated
- you’re not an employment business supplying either staff or workers, or both
- your customer has not given written confirmation that they are an end user
How does it work?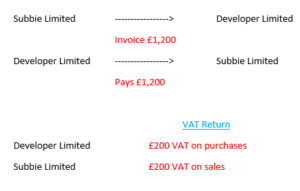
Under the existing VAT rules, Subbie Limited is invoicing Developer Limited for £1,000 of standard rated work.
Subbie Limited raised an invoice for £1,000 plus VAT at 20% of £200, total £1,200.
Developer Limited would have then paid £1,200 to Subbie Limited.
Subbie Limited would pay £200 over to HMRC in its next VAT return.
Developer Limited would reclaim £200 from HMRC on it’s next VAT return.
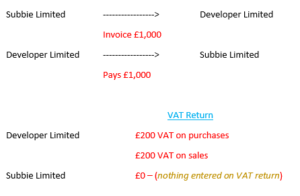 Under the new VAT reverse charge rules, Subbie Limited will raise an invoice for £1,000 with a note to indicate that VAT at 20% of £200 should be declared by Developer Limited.
Developer Limited will then pay the £200 over to HMRC in its next VAT return, but also reclaim £200 from HMRC, giving a zero net effect.
There is no provision to “opt out of the regime” or obtain any form of exemption certificate from HMRC.
However, the new regime will not apply where:
- Services are supplied to the end user, such as the property owner, or directly to a main contractor that sells a newly completed building to the customer;
- The recipient makes onward supplies of those construction services to a connected company;
- The supplier and recipient are landlord and tenant or vice versa, or
- The supplies are zero-rated.
What actions should be taken?
Construction businesses should:
- Review supplies made to and received from other VAT registered contractors to establish whether these will be subject to a reverse charge from 1st March;
- Consider the adaptions that will need to be made to their accounting systems to deal with this change and;
- Consider the impact on their cash flow from 1st March, and if there are any other ways to mitigate this impact.
The MDH team are here to support you
If the above will have an impact on your of your business, please book in a 30 minute call with Michael or Natalie to discuss.
Join our private Facebook page for Croydon & Surrey Business Owners.